Byram, MS
Life Insurance in Byram With Straight Answers and No Pressure
We help individuals and families choose term life, whole life, universal life, final expense coverage, mortgage protection and variable life insurance. You hear plainly what each policy does and what it costs, then you decide. We meet in our office, by phone or by video, including with neighbors in Jackson and Richland.
- Free quotes by phone
- Talk to a live person
- Virtual appointments available
- Yearly reviews we schedule
A Local Agent in Byram
Life Insurance Byram is a local agency for people and families who want their coverage explained in clear terms. We work out of our office and meet by phone or video when that suits you better. Plenty of clients begin with a single question, such as how much coverage they need or whether whole life is worth paying more for, and we answer it briefly first.
Each plan begins with your circumstances and the monthly amount you can comfortably afford, not a ready-made package. It could be a simple term policy for the years your children live at home, final expense coverage so your kids are not stuck with funeral costs, or mortgage protection that helps your family keep the house. Whatever you pick, the same agent works with you before and after you sign.
- License
- Life & Health Insurance license; Variable Life & Variable Annuity license
- Certifications
- Investment Adviser Representative (IAR)
Life Insurance Coverage We Write
Our Life & Health Insurance license, our Variable Life & Variable Annuity license and our Investment Adviser Representative (IAR) credential let us explain every kind of life coverage, from basic term life to variable life linked to market subaccounts. Term life pays out over a set number of years at a fixed premium. Whole life, universal life and final expense insurance are permanent options suited to different budgets and goals, and mortgage protection helps your family keep up the house payment. Each page below explains who a policy suits and what sets its price.
Term Life Insurance
Affordable coverage for a set number of years, matched to the mortgage, the kids and the income your family counts on.
Whole Life Insurance
Permanent coverage with a premium that never rises and cash value that builds over time, explained plainly so you can judge whether it fits your budget.
Universal Life Insurance
Permanent coverage with premiums you can adjust, plus a clear explanation of what keeps the policy in force and what can make it lapse.
Final Expense Insurance
A smaller whole life policy sized to cover funeral costs, medical bills and other final expenses, with fixed premiums and coverage that does not expire.
Mortgage Protection
Life coverage sized to your home loan, so your family gets the money and decides whether to pay off the mortgage or keep making payments.
Variable Life Insurance
Permanent coverage whose cash value is invested in funds you choose, with the upside and the risk laid out plainly before you sign.
How You Get Covered
The path to a policy is shorter than most people think. Here is what happens between your first call and the day your policy shows up.
- 1
One quick call
A live person picks up. We ask who depends on you, what you owe and what you can afford each month, then give you a free quote.
- 2
Compare your choices
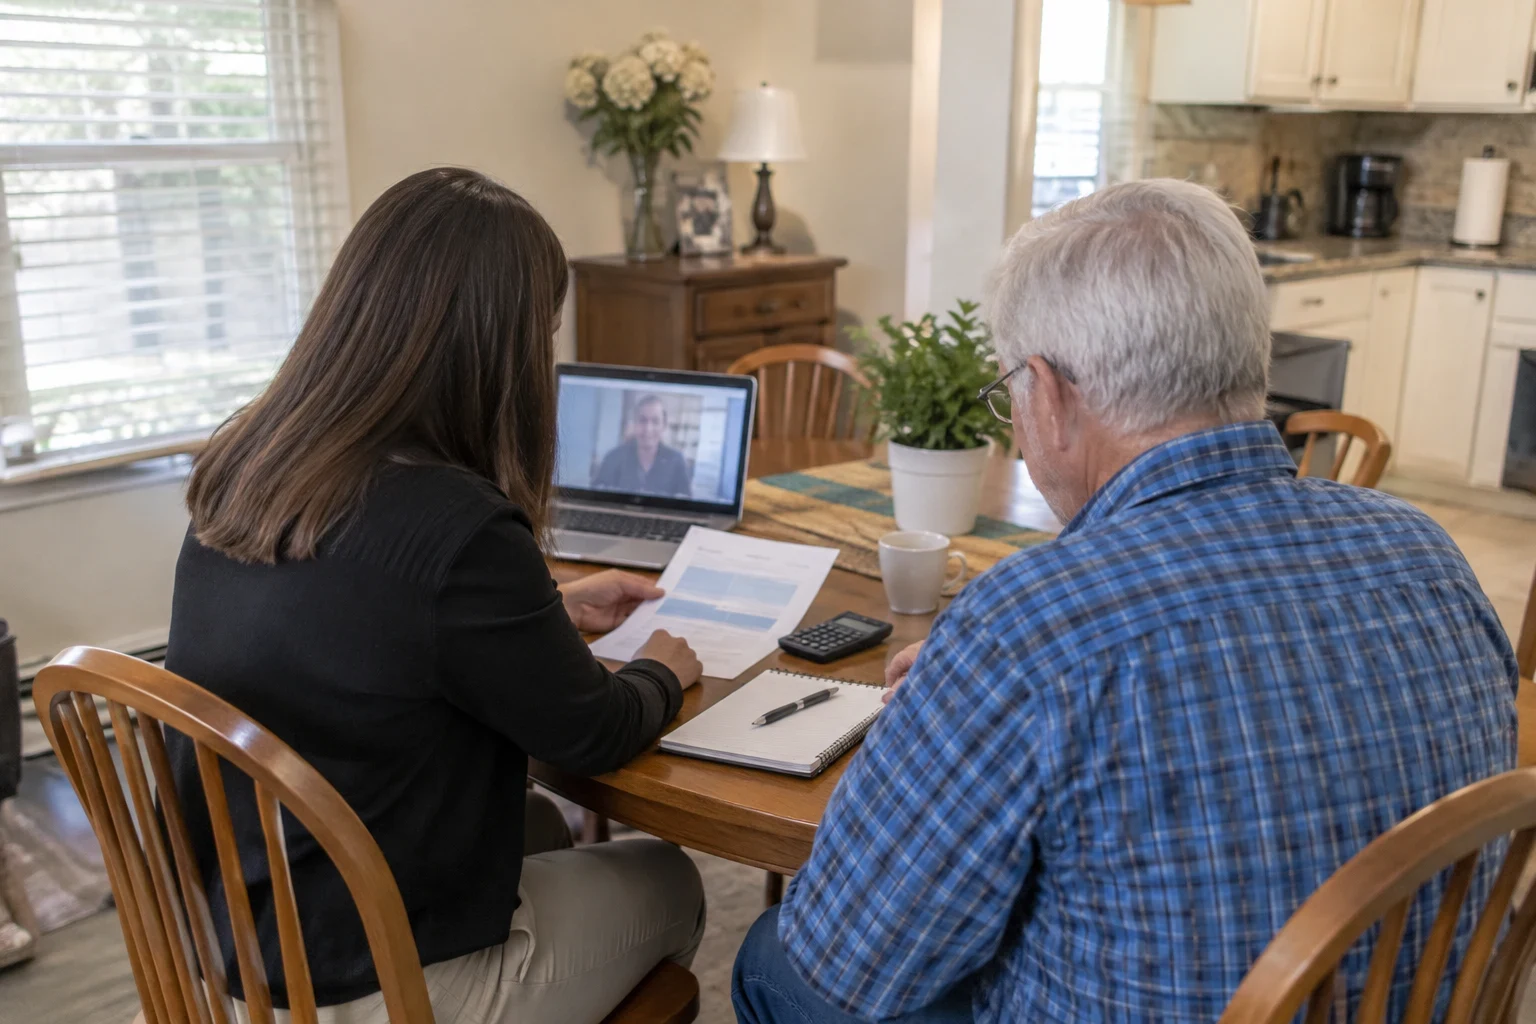
When you want a closer look, we arrange a video call or an office visit. We set two or three options next to each other and explain the trade-offs in everyday words.
- 3
Applying and underwriting
After you pick a policy, we go over the application questions with you on a call or at your appointment, and we pass everything along to the insurer. Depending on the policy, they may ask for a paramedical exam, your doctor's records or only health questions. We tell you which in advance and keep you updated while you wait.
- 4
We review the policy with you
Once you are approved, we walk through the policy together and hand you a one-page summary. We also make sure your beneficiaries are recorded correctly before you put it away.
- 5
Ongoing check-ins
Every year we schedule your review and look over your beneficiaries. If your family ever has to file a claim, we stay with them through each step.
How We Work With Families
Shopping for life insurance should be a back-and-forth talk, not a sales routine. This is how we work with you before your policy begins and in the years that follow.
- 01
Licensed for every topic we cover
We carry a Life & Health Insurance license, a Variable Life & Variable Annuity license and the Investment Adviser Representative (IAR) credential. So when you ask about variable life and how its cash value rises and falls with the market, the answer comes from someone licensed to give it.
- 02
Plain talk on your timeline
We describe each option in ordinary words, and you choose when to decide. If term life covers what you need, we say so. If permanent coverage fits better, we show you the figures behind it.
- 03
The same local agent answers
A live person takes your call, and it is the local agent who handles your policy. There is no phone tree, and you never have to retell your story to a stranger.
- 04
Everything on one sheet
Every client gets a single page listing each policy, what it costs and what it covers. Put it in a drawer or hand a copy to your spouse, and no one has to search a forty-page contract for the essentials.
- 05
Still here years later
We book your review every year and check who is set to receive the money. New baby, a move or a job change? Tell us, and we update your coverage within a week.
What Shapes Your Life Insurance Price
Two people born the same year can get quotes that are far apart. A premium reflects the insurer's view of how likely a claim is, how much coverage you want and how long it has to last. Here are the factors that count most, so your quote makes sense when you see it.
Every quote is free and based on what you share with us by phone. The insurer settles the final premium after underwriting, and we tell you right away if anything changes.
- Your age when you apply
- The premium is set by how old you are when the policy is issued. Starting at 35 instead of 45 can make a big difference over time, and a term life rate stays locked for the whole term.
- Your health and tobacco use
- Insurers look at your medical history, medications, height and weight, and whether you use tobacco or nicotine. Tobacco by itself often moves you into a higher rate class. Some policies swap the exam for a brief list of health questions.
- The amount of coverage
- More coverage raises the premium, but doubling the amount rarely doubles the price. We match the figure to real needs like replacing a paycheck, clearing a mortgage or paying for your kids' education, so you are not buying coverage you will never use.
- Term or permanent coverage
- Because term life ends after a fixed stretch of years, it usually buys the most coverage for the smallest premium. Whole, universal and variable life stay in place for life and build cash value, which makes each dollar of coverage more expensive.
- Optional riders
- Every add-on raises the premium a little. Two popular ones cover your children or pay out part of the benefit early after a terminal diagnosis. We tell you plainly which ones make sense for your family and which you can leave off.
Serving Byram and Nearby Towns
We are based in Byram and work with families across the area, including Jackson, Richland, Florence, Pearl, Clinton, Ridgeland, Flowood and Crystal Springs. Because so much of our work happens by phone and video, distance is rarely an issue. If you prefer to sit down in person, our office is an easy drive from most of these towns.
- Byram
- Jackson
- Richland
- Florence
- Pearl
- Clinton
- Ridgeland
- Flowood
- Crystal Springs
Virtual appointments are available, so you can get a free quote and talk through your options without leaving home.
Life Insurance Questions We Hear Often
Something not covered here? (601) 327-3281
How much coverage should I buy?
Think about what your family would have to pay if your income stopped: the mortgage, any debts, a few years of regular living costs and goals such as college. Take away your savings and any coverage from work. We work through the math with you on the first call, and the answer often lands above or below what people expected.
How is term life different from whole life?
Term life covers a stretch of years you choose, commonly 20 or 30, and is the cheaper option. Whole life stays in place for your whole life at a premium that never changes, and it builds cash value you can borrow against. Young families protecting an income tend to pick term. Whole life suits people who want coverage for life or want to leave money whenever they die.
Is a medical exam required?
It depends on the policy. Some call for a brief paramedical exam and blood draw. Others, many final expense plans among them, use health questions only. Going without an exam can bring a higher price or a smaller coverage limit. You will know which type you are applying for before you begin.
What happens when my family needs to file a claim?
We handle it with them. We meet in person, help them obtain the death certificate, go through the insurer's claim forms line by line and keep in contact until the payment comes. We also review your beneficiaries every year so the money reaches the people you picked.
Can we do this by video rather than in person?
Yes. We offer virtual appointments, and plenty of clients finish everything by phone and video. If you prefer to meet face to face, you can schedule a visit to our office.
What if something changes after I have a policy?
Let us know. Whether it is a new baby, a new home or a new job, we update your coverage within a week of hearing from you. Every client also gets a yearly review that we schedule, so nothing gets missed.
Will I be pushed to buy?
No. We explain each option and the timing is up to you. A free quote carries no obligation, and you can talk it over with your family for as long as you need.
Find Out What Coverage Would Cost Your Family
One phone conversation gets you a free quote and a clear picture of which policy fits. If you want more time, we can book a video meeting or a sit-down at our office for later in the week.